How to Send Money To/From Iran
OFAC sanctions against Iran impose strict restrictions on financial transactions between Iran and other countries, including the United States and Europe. The main goal of these sanctions is to influence Iran’s policy. They are aimed at ending support for terrorism, limiting the development of the nuclear program, and drawing attention to human rights violations, as well as isolating Iran from the global financial system. They include a ban on banking operations, freezing of assets, and other financial restrictions.
It is crucial to understand the stakes involved. Violating OFAC sanctions is a strict liability offense. As of 2026, civil penalties for sanctions violations can reach up to $368,136 per violation or twice the value of the transaction, whichever is greater. These penalties apply even if the violation was unintentional.
For private individuals wishing to send money to Iran, these restrictions present significant challenges. This approach is intended to limit Iran’s economic resources for actions that may threaten international security. If you need assistance, contact lawyer for OFAC licensing.
Family remittances may be permitted under a general license, but the payment route decides whether the funds arrive or get blocked. We confirm which license covers your transfer and advise on a compliant banking route.
Check if my transfer is legal →Updated October 2026
Is It Legal to Send Money to Iran in 2026?
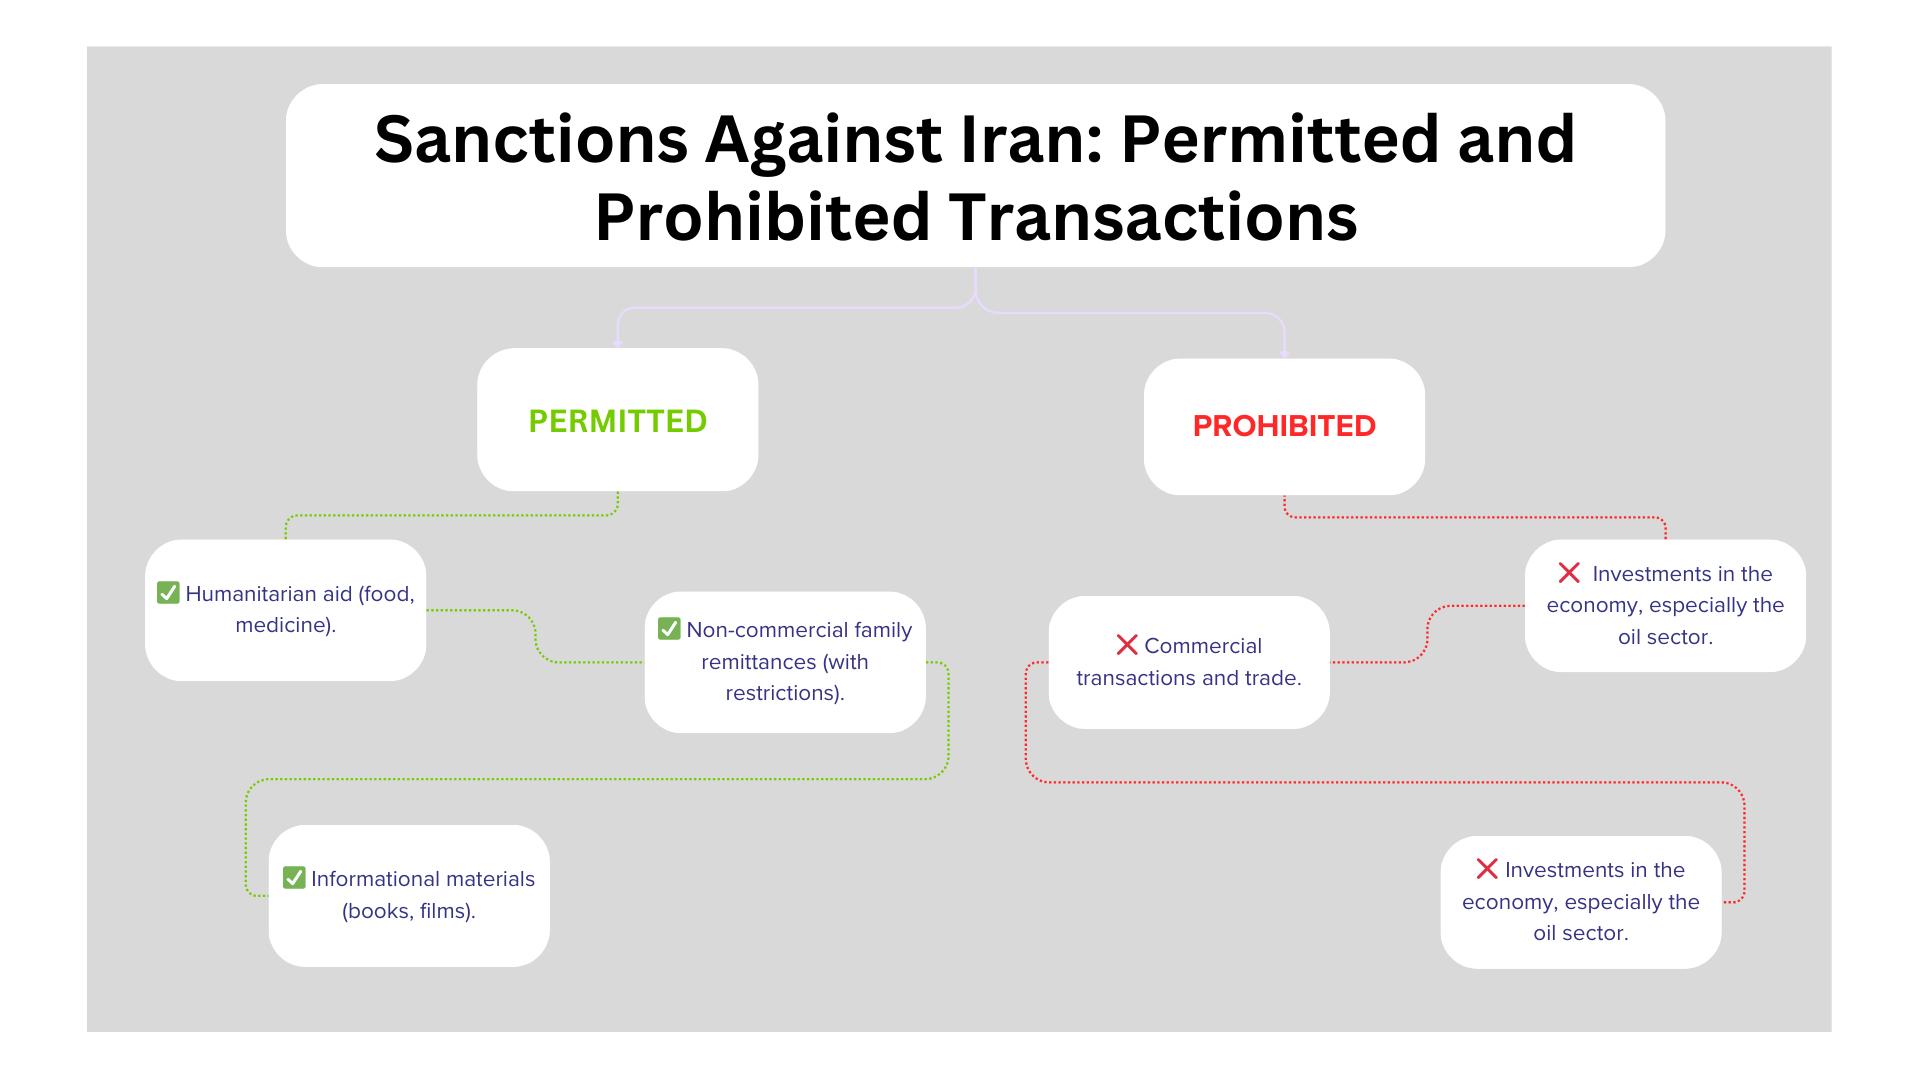
Sending money to Iran is not automatically unlawful, but it is tightly restricted. A transfer may proceed only when a General or Specific OFAC License authorizes it. Non-commercial personal remittances, such as family support, can qualify under 31 CFR § 560.550 if they go through the formal banking system and involve no SDN-listed party. Transfers outside these conditions can be blocked, and the funds may be frozen or returned.
Transfer Money to/from Iran
Transferring money between Iran and the USA or Europe has become extremely difficult due to strict restrictions by the Office of Foreign Assets Control (OFAC). Banking relations between the countries are officially prohibited. This means that traditional methods, such as SWIFT, are unavailable. The lack of access to such standard tools forces people to look for alternative ways to transfer money from their bank accounts to Iran. For specific rules on bank wire transfers to Iran and which payment channels remain OFAC-compliant, see the sections below. Most often, private intermediaries or small financial services in a third country operating outside the traditional banking system are used for this purpose. Note: cryptocurrency transfers involving Iran are not a legal alternative — they carry the same OFAC prohibitions as direct bank transfers.
Since direct “U-Turn” transactions (Iran-US) are prohibited, legal transfers typically involve a transparent banking chain through a third country (e.g., Turkey, UAE, or EU). The legal route usually looks like this: Iranian Bank (Non-SDN) → Third Country Bank → Correspondent Bank → US Bank. However, this is only permissible if the underlying transaction is authorized by a General or Specific License.
To make a money transfer to Iranian banks, it is necessary to obtain a license or use the services of intermediaries. Intermediaries usually provide the opportunity to bypass sanctions, but this is often associated with high risks, including the possibility of fraud or legal complications. In addition, such transfers are often accompanied by high fees.
Many intermediaries operate via the “Hawala” system (informal value transfer). While common in the region, using an unlicensed money transmitter is a violation of US law (31 CFR § 560.550 requires funds to pass through the formal banking system). Using Hawala can lead to funds being seized without recourse.
Before conducting a transaction, it is necessary to determine whether the transfer falls under the current OFAC licenses. If the transaction does not fall under these licenses, you will need to apply for a special permit. For example, if you are sending money to Iran to support your family (personal remittances), it is important to provide a detailed description of the purpose of the transfer and prove that it is a non-commercial operation.
Our company provides professional legal assistance in this process. We will help you gather the necessary documents, submit the application, and monitor its review, ensuring transparency and security for your money transfer operation to Iran.
How to Send Money Legally
Don’t rely on forums. Get professional legal advice on family remittances, student support, and asset transfers permissible by OFAC.
Get Legal AdviceOFAC General License
OFAC General licenses allow certain transactions to be conducted without obtaining additional permissions. The existing general licenses are intended to facilitate financial operations that do not pose a threat to the security and policies of the United States. Such licenses permit personal money transfers if they are non-commercial. Other authorized cash transactions include payment of medical expenses and support for humanitarian projects. These operations often involve funding patient treatment, supporting charitable organizations, or providing basic needs for families in difficult situations.
To be specific, the following General Licenses are most relevant for individuals:
- 31 CFR § 560.550: Authorizes non-commercial personal remittances (e.g., family support) to/from Iran, provided they are processed through the banking system and do not involve sanctioned (SDN) entities.
- 31 CFR § 560.543: Authorizes the sale of real property in Iran and transfer of proceeds to the US, only if the property was acquired before the individual became a US person or was inherited.
- General License M-2: Covers certain exports of agricultural commodities, medicine, and medical devices.
- General License D-2: Facilitates the export of software/hardware to support internet freedom in Iran.
You do not need to notify regulatory authorities if you are conducting operations under a general license. However, it is important to ensure that none of the parties to the transaction are included in OFAC SDN list. If one of the parties to the transaction is on this list, the transaction will be blocked. In such cases, this may lead to fines or other legal consequences. If you want to learn how to remove your name from the SDN list, contact our lawyers. We will assist you in resolving this issue, guiding you through all stages of the process.

| License | Permitted transactions | Conditions |
|---|---|---|
| 31 CFR § 560.550 | Non-commercial personal remittances (e.g., family support) | Processed through the banking system and do not involve sanctioned (SDN) entities |
| 31 CFR § 560.543 | Sale of real property in Iran and transfer of proceeds to the US | Acquired before the individual became a US person or was inherited |
| General License M-2 | Exports of agricultural commodities, medicine, and medical devices | — |
| General License D-2 | Export of software/hardware to support internet freedom in Iran | — |
OFAC Special License
Special OFAC licenses from the Treasury Department are required for operations not covered by general licenses. These include complex transactions, such as transferring large sums, purchasing or selling real estate, as well as commercial deals. For example, if you plan to invest in an Iranian business or sell property in Iran, you will need a special license.
While selling inherited property often falls under a General License (§ 560.543), purchasing new property or selling property acquired after moving to the US almost always requires a Specific License. Misinterpreting this distinction is a common reason for blocked funds.
To send money to an Iranian bank account under a special license, you need to submit an official application. The application must include information about all parties involved in the transaction, the transfer amount, and its purpose. For example, if you are transferring a significant amount of money to pay for a contract, copies of the contract and financial documents must be attached.
The application process is quite complex and requires compliance with all requirements. Our team of lawyers will help you complete the application, prepare the documents, and ensure that the process goes as smoothly as possible. We can also provide consultation on additional requirements or potential risks in your situation.
Transferring Money to/from Iran with Cryptocurrency
The use of cryptocurrencies for transferring money between Iran and the USA has become popular due to sanctions regulations on traditional financial channels. OFAC allows the use of cryptocurrencies, but this method also has its risks. Cryptocurrency transactions are not always regulated in the same way as traditional financial operations. This creates opportunities to bypass Iran sanctions but can also lead to serious legal consequences.
The landscape for cryptocurrency has changed drastically. In 2025 and early 2026, OFAC began sanctioning entire cryptocurrency exchanges and wallet clusters associated with Iranian traffic (e.g., recent actions against platforms like Zedcex). Blockchain analytics firms (like Chainalysis) now flag wallets interacting with Iranian IPs. Using USDT (Tether) for transfers is no longer a “grey area”—it is strictly monitored, and assets can be frozen on the blockchain level.
When sending money to Iran using cryptocurrencies, it is important to comply with all applicable rules and regulations. For example, you must know the exact source of funds and ensure that all parties involved in the transaction adhere to OFAC rules. If the transaction is found to be illegal, it may result in funds being blocked or legal proceedings. Cryptocurrencies provide speed and convenience, but you should not underestimate the risks associated with their use. If you want to learn more about the safe use of cryptocurrencies for transfers, contact our lawyers. We will provide you with recommendations for optimal solutions.

Personal Remittances and Family Gifts
Under 31 CFR § 560.550, non-commercial personal remittances to or from Iran, for example support for family members, are authorized when they are processed through the banking system and do not involve sanctioned (SDN) entities. Payments tied to goods, investments or sanctioned parties are not covered and need a separate General or Specific License.
How to Send Money to Iran from the USA Legally
To send money to Iran from the USA, the transfer must qualify as a non-commercial personal remittance under 31 CFR § 560.550 — family support, emergency assistance, or similar personal transfers, not payments tied to goods, investments, or sanctioned entities. Since there’s no direct banking relationship between the U.S. and Iran, funds route through a correspondent or third-country bank, which adds time and fees compared to a domestic wire.
Transfers must go through a registered bank, credit union, or licensed broker-dealer, and the institution will verify the transfer’s purpose, your relationship to the recipient, and the source of funds under standard AML/KYC procedures — the same checks apply whether you’re sending or receiving. Some personal transfers qualify automatically under existing general licenses, without a separate OFAC application; anything connected to a SDN-listed party does not.
Keep receipts, confirmations, and correspondence documenting the transfer’s purpose — if OFAC or your bank later asks questions, this is what supports your explanation.
Exchange Houses, Intermediaries and Payment Agents
Because direct banking relations between the United States and Iran are prohibited, people are often offered private intermediaries or small financial services in a third country that operate outside the traditional banking system. These routes carry high risks, including fraud, high fees and legal complications.
A transfer can be blocked or returned when the route is not backed by a license, or when a blocked Iranian party is indirectly involved: under 31 CFR § 560.211, property in which the Government of Iran or an Iranian financial institution has an interest is blocked. Informal value transfer systems such as Hawala are not a safe alternative. Using an unlicensed money transmitter violates US law, and funds sent this way can be seized without recourse.
A lawful structure typically uses a transparent banking chain through a third country, for example Turkey, the UAE or the EU, and only when the underlying transaction is authorized by a General or Specific License.
What Documents Your Bank May Ask For
Banks verify the purpose of the transfer, your relationship to the recipient and the source of funds under standard AML/KYC procedures. It is useful to have ready:
- a description of the transfer: purpose, amount and involved parties;
- identification details of the parties: name, address, contact information;
- your relationship to the recipient;
- financial documents confirming the source of funds and the final destination;
- a cover letter or justification explaining why the transfer is needed;
- contracts, invoices or other agreements, if the transaction is not purely personal.
Keep receipts, confirmations and correspondence documenting the purpose of the transfer. If OFAC or your bank later asks questions, these documents support your explanation.
Receiving Money from Iran: Inheritance and Sale of Property
Money coming from Iran is assessed under the same rules. Under 31 CFR § 560.543, the sale of real property in Iran and the transfer of the proceeds to the US is authorized only if the property was acquired before the individual became a US person or was inherited. Buying new property, or selling property acquired after moving to the US, almost always requires a Specific License. For inherited assets, see our guide on Iran inheritance and OFAC licensing.
Are Wire Transfers to Iran Allowed?
All Iran wiring funds transfers originating from the USA (or controlled by US financial institutions) are considered prohibited unless there is an appropriate license from OFAC. This applies to both bank transfers and electronic payment systems.
American banks and payment services are required to block transactions that violate sanctions against Iran. Failure to comply with the rules threatens the remitting bank with large fines, so financial institutions prefer to strictly control any transfers.
OFAC issues two types of licenses regulating operations with Iran:
- General License
A general license is a general authorization allowing certain groups of operations to be carried out without an individual application to OFAC. This category includes humanitarian transactions, the supply of pharmaceuticals or food products. Any action that does not fall within the scope of a specific general license remains prohibited.
- Specific License
A specific license is permission to conduct a certain operation, issued based on the review of an individual application. To obtain this type OFAC license it is necessary to collect the following documents for application:
- Detailed description of the operation (purpose, amount, involved parties);
- Identification details of the parties (name, address, contact information);
- Financial documents confirming the source of funds and the final destination;
- Cover letters or justifications explaining the necessity of the transaction;
- Additional documents (contracts, invoices, or other transaction-related agreements).
Write an application in the prescribed form indicating information about the applicant, the purpose of the transaction, and its compliance with the sanctions exception, as well as the grounds on which you are requesting a special permit. All documents and the application must be prepared in English.
The application is submitted to the OFAC Licensing Division. This can be done via the OFAC online platform or by post.
The processing time for the application may vary from several weeks to several months, depending on the complexity of the operation and the volume of information. OFAC will notify the applicant of its decision.
If approved, the applicant receives a special license specifying the conditions to wire money. In the license, OFAC usually indicates the maximum permitted amount, categories of recipients, and specific purposes of the transfer. Any deviation beyond these limits is prohibited and requires updated authorization.
Even after obtaining a license, the bank or payment system will closely monitor transactions, checking compliance with the conditions. Upon request from OFAC, they are obliged to provide documentation and justification for each transaction. In cases where the financial institution doubts the legality or purpose of the payment, it may temporarily block the transfer until it receives the necessary explanations from the client and/or OFAC.
Our legal company will help assess risks, prepare an application for a special licence, and develop a payment scheme compliant with sanction requirements.
How an OFAC Lawyer Can Help if Funds Are Returned?
Under the strict sanctions regulations against Iran, transactions with local entities may be subject to blocking or return of funds. However, not all cases are a direct result of intentional violation of the law. Often, the reasons lie in the absence of the necessary license, inaccuracies in documents, or incomplete understanding of OFAC rules:
- Non-compliance of the transaction with established exceptions. When transferring funds with sanctioned jurisdictions, a special or general license is required. If money is sent without the appropriate authorization, the bank may freeze the payment and return the funds;
- Errors in documentation. Several incorrect lines in the payment order, lack of detailed information about the recipient, issues with SWIFT codes — all this may lead to the financial institution considering the operation suspicious and halting it;
- Joint violation of sanctions. Under 31 CFR § 560.211, property in which the Government of Iran or an Iranian financial institution has an interest is blocked — even indirect involvement of a blocked Iranian party in a transaction can cause a bank to freeze or return the funds. Even indirect involvement in a transaction by a person from the OFAC Black List may force the bank to return the money;
- Audit. Fearing fines, banking structures often apply heightened due diligence control measures. If they have the slightest doubts about the legitimacy of the transaction, the payment may be declined or returned.
A lawyer specializing in sanctions legislation will analyze the details of the return: reasons, accompanying documents, the positions of the bank and OFAC. This will help identify whether there was an error in the documentation or actual signs of sanctions violations.
If the transaction simply requires additional information or clarifications, the solicitor will prepare letters with explanations. Your lawyer will also gather the necessary documents so that the payment can be safely processed again.
If interaction with Iranian counterparties is necessary (for personal transfers, non-commercial purposes, or special programs), an individual OFAC licence may be required. A lawyer will handle the application process, preparation of business plans, and justifications for the regulator.
Often, the decisive factor is communication with the bank since it’s important to prove that the transaction does not violate sanctions or comply with one of the general licences. A lawyer will be able to take on the negotiations, ensuring proper interaction between all parties.
To avoid repeated mistakes, the OFAC lawyer will develop a set of standard documents and procedures (KYC, counterparty checks, payment order forms) that will help to correctly conduct settlements in the future and avoid freezes.
Our company has experience and expertise in matters of interaction with OFAC, preparing the necessary applications, and conducting negotiations with banks. If you have encountered a funds return or want to protect your transactions from blockages in advance, contact us. We will provide qualified assistance, prepare documentation, and ensure compliance with all requirements of sanctions legislation.
| Reason | Possible Outcome |
|---|---|
| Non-compliance of the transaction with established exceptions. | bank may freeze the payment and return the funds |
| Errors in documentation. | operation suspicious and halting it |
| Joint violation of sanctions. | bank to freeze or return the funds |
| Audit. | payment may be declined or returned |
Comply with U.S. OFAC Sanctions
OFAC regularly imposes multimillion-dollar fines on banks, payment systems, and private companies caught circumventing or violating sanctions against Iran. In particularly severe cases, even criminal liability or blocking access to the American financial system is possible.
The publication of facts about sanctions violations often leads to a loss of clients and partners, as well as distrust in future deals. In the context of the international market, companies and individuals cannot ignore OFAC requirements, as they risk losing important financial instruments and accounts in banks operating in US dollars.
Any transaction deemed suspicious may be blocked indefinitely, resulting in the loss of control over financial assets until all circumstances are clarified.
Organizations that frequently conduct transactions with sanctioned entities must carry out systematic audits to identify potential vulnerabilities. As part of the audit, specialists analyze payment documents, transfer routes, counterparties, and compliance with sanction lists.
Consultation with lawyers specializing in sanctions law will help the company avoid irreversible consequences and protect its reputation. Lawyers will assist in preparing OFAC licences, check counterparties, interact with banks, or represent interests in potential disputes.
OFAC Iranian Lawyers
If you encounter difficulties when trying to transfer money to Iran or from Iran, our team of lawyers is ready to help. We specialize in issues related to OFAC sanctions and have extensive experience with licensing. Our goal is to provide you with a safe and legal way to conduct financial transactions. In many cases, these issues are closely connected with sanctions in Iran, and people often wonder if it is legal to send money to Iran.
We will help you determine which license is required in your case and will assist you at every stage. We will also ensure that all documents are thoroughly reviewed and that your activities comply with current legislation. With us, you will receive professional support that will help you avoid mistakes and minimize risks. Our specialists are ready to answer all your questions and find the optimal solution for your situation. If the transfer relates to funds inherited from Iran, additional licensing requirements apply. See our guide on Iran inheritance and OFAC sanctions.
FAQ
Is it legal to send money to Iran?
Sending money to Iran is not automatically unlawful, but it is tightly restricted. A transfer may proceed when a General or Specific License authorizes the underlying transaction, and personal remittances can qualify when they are non-commercial, use the banking system, and avoid sanctioned entities. Transfers outside applicable authorization can be blocked and may create legal consequences.
Can money be transferred between Iran and the United States or Europe through ordinary banking channels?
For transfers involving Iran and the United States or Europe, ordinary banking channels are generally unavailable because official banking relations are prohibited, including SWIFT. A lawful structure may use a transparent chain through a third-country bank and a correspondent bank, but it is allowed only when a General or Specific License authorizes the underlying transaction.
Can family support payments be sent to Iran?
Family support payments may fall under a General License when they are personal and non-commercial. The sender should provide a detailed explanation of the transfer’s purpose, show that it is not commercial, and ensure processing through the banking system without an SDN party. The payment route still matters, because funds can be blocked if the conditions are not met.
When is a Special OFAC License required for sending money to Iran?
A Special License is needed for transactions that do not fit within a General License. Examples include certain large transfers, commercial transactions, and some real-estate dealings. The application must identify every participant, state the amount and purpose, and include supporting materials such as contracts and financial records when relevant.
Can cryptocurrency be used to transfer money to Iran?
Cryptocurrency is not a risk-free workaround for transfers involving Iran. Transactions must comply with OFAC requirements, including verifying the source of funds and the parties involved. Iranian-linked exchanges, wallets, and USDT activity are subject to monitoring, and assets may be frozen. An unlawful transaction can result in blocked funds or legal proceedings.
What is 31 CFR § 560.550?
31 CFR § 560.550 is the Iran sanctions provision that authorizes non-commercial personal remittances, such as family support, to or from Iran. The transfer must be processed through the banking system and must not involve sanctioned (SDN) entities or finance prohibited operations. Commercial or business-related transfers are not covered.
Can I receive a gift or money from Iran?
Non-commercial personal remittances, including family support, are covered by 31 CFR § 560.550 both to and from Iran, provided they pass through the banking system and no SDN party is involved. Transfers connected to a business, goods or investments are not covered and may need a Specific License. If the money comes from an inheritance or the sale of property, separate licensing rules apply under 31 CFR § 560.543.